Why Cannot I Stay on My Parents Insurance
Once you're stationed away from your parents' home and driving a car they don't own, their policy usually stops covering you right.
Free to compare
Stationed across the country, still on mom's policy
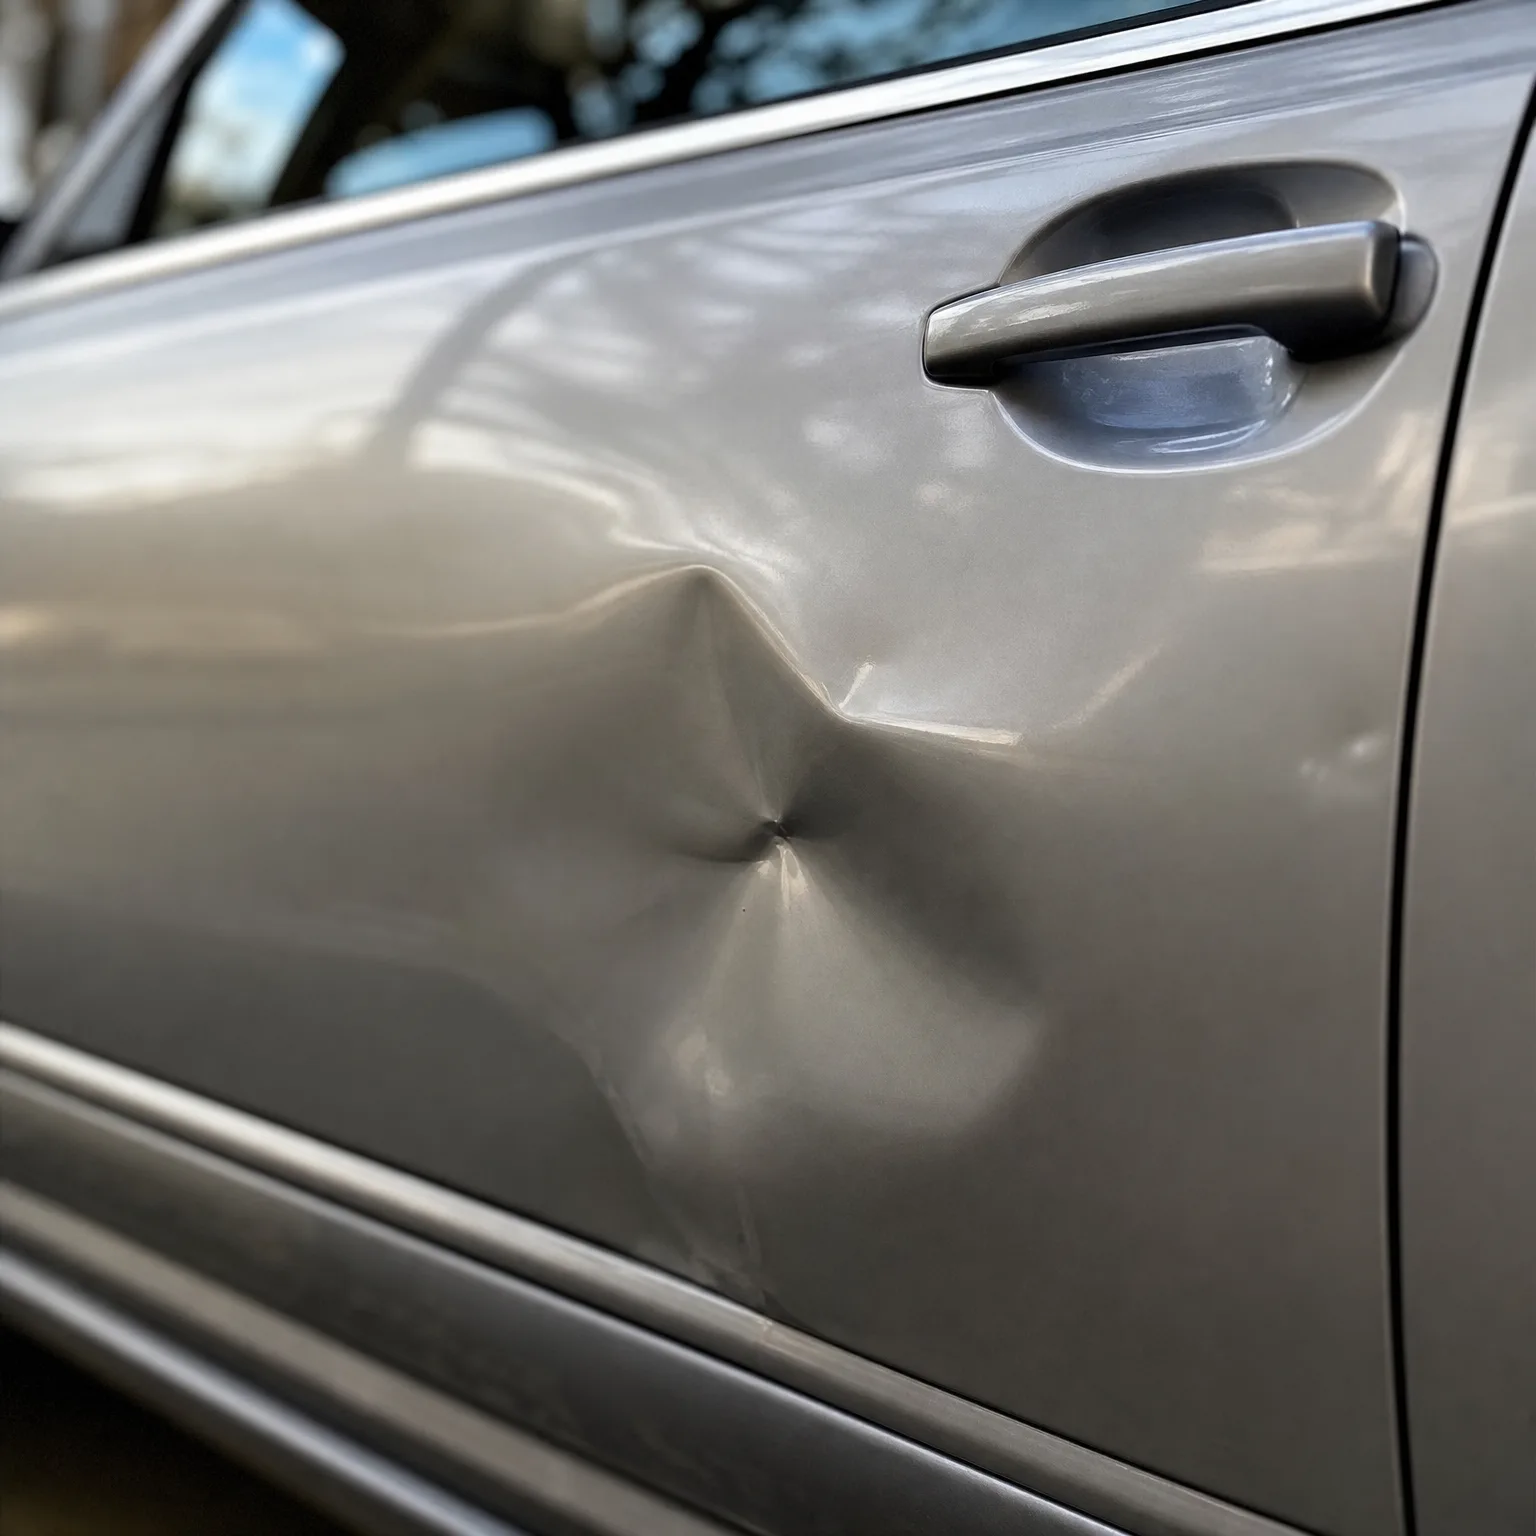
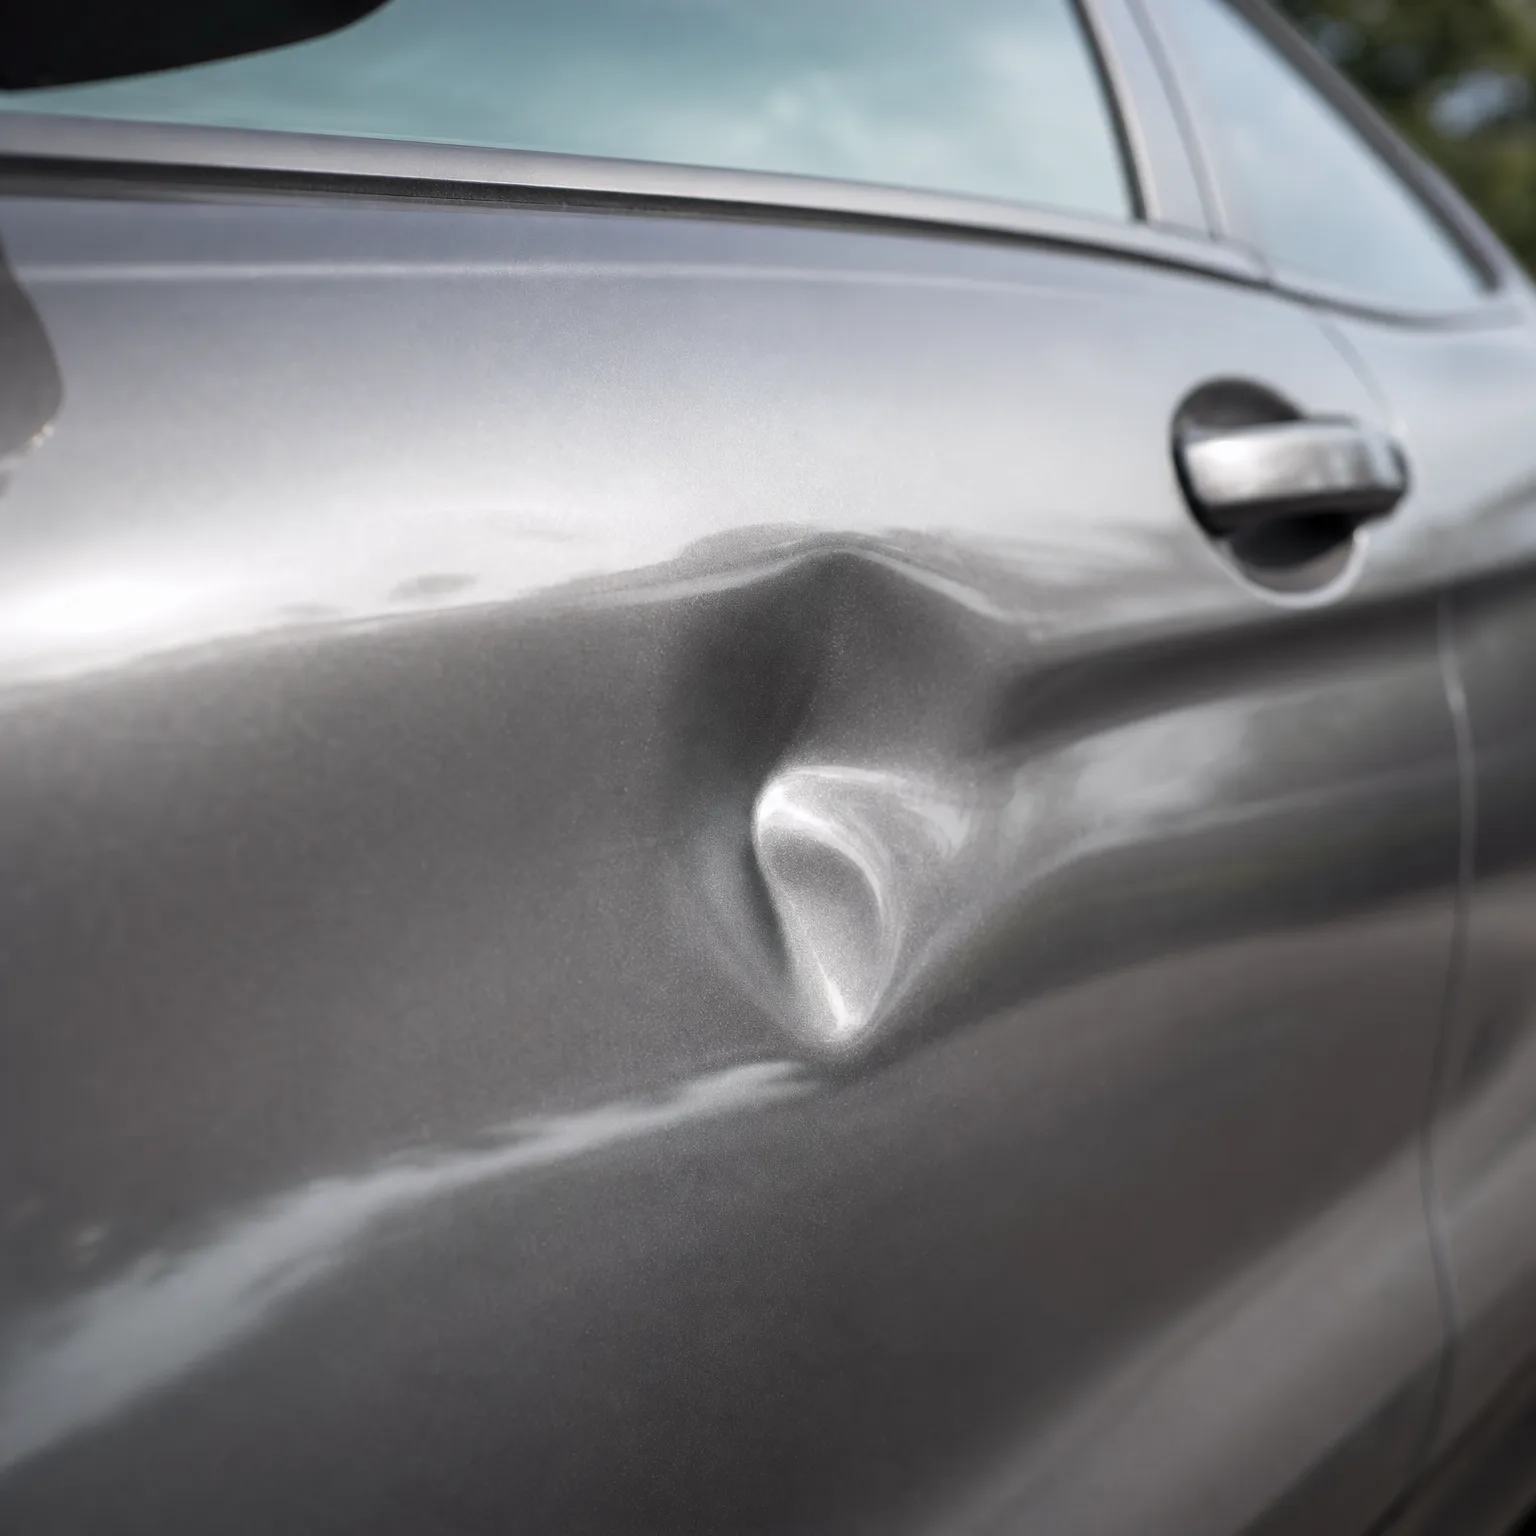
A service member stationed in another state kept his car titled and insured under his parents' policy back home because it was easier and cheaper. He didn't think much of it until his car got hit in a parking lot near base and the claim got delayed while the insurer asked why the car and driver were both permanently located somewhere other than the policyholder's address.
The insurer didn't deny the claim outright, but it flagged the policy for review and asked him to either re-register the car in his new state or add himself as a rated driver with his actual location on file. He ended up getting his own policy in the state where he was stationed, using his military orders to qualify for the legal residency exception many states allow. His new policy cost more than his share of his parents' plan, but it matched where he actually lived and drove, and the next claim he filed went through without any questions.
Can I use my home state address instead of switching to my duty station?
Often yes, and this is one of the clearest advantages of military life. Most states let active-duty service members keep their legal residency and vehicle registration in their home state even while stationed elsewhere, and insurers generally honor that if you can show military orders.
This matters because it means you don't have to re-register your car or switch insurers every time you get new orders. But the insurer still needs to know where the car is actually garaged most of the time, since that affects risk and coverage. Check with your insurer directly about what documentation they want, because the paperwork varies and some require it annually.
The real issue isn't your age or address. It's where your car actually lives and who actually drives it.
Now that you know what coverage you actually need, compare quotes built around where you're really stationed.
Staying on your parents' policy anyway
If you do
You risk a claim getting delayed or denied if the insurer finds out the car's real location and driver don't match the policy. You're also not building your own insurance history, which matters later for rates. It may work short-term but it's fragile.
If you don't
You get a policy that matches your actual situation, so claims go through without extra scrutiny. You start building your own driving and insurance record. It may cost more upfront, but it's coverage you can actually rely on when something happens.
Can I get military car insurance discounts if I'm not deploying yet?
Yes, many military discounts don't require deployment at all. They're based on your active-duty status itself, not your orders. Ask any insurer you're considering whether they offer a military discount and what proof they need, usually just a military ID or LES. Check whether the discount applies only to certain states or coverage types, since that varies by insurer.
How do I insure a car I'm leaving with my spouse while deployed?
You keep the policy active with your spouse listed as a driver, or you transfer it into their name if they'll be the primary user. The right choice depends on who's actually driving and whether you want to keep your own insurance history building. Tell your insurer about the deployment, since many offer to adjust coverage or pause certain parts of it while you're away.
What happens to my insurance if I store my car during deployment?
You can usually switch to a reduced coverage level instead of canceling entirely. This keeps your policy active, which protects your insurance history, while lowering your cost since the car isn't being driven. Ask your insurer specifically about storage or comprehensive-only coverage, since not every insurer offers it the same way or under the same terms.